Is HELOC Interest Tax Deductible in 2026? The Rules in Plain English

Is HELOC Interest Tax Deductible in 2026? The Rules in Plain English
Is HELOC interest tax deductible in 2026? Sometimes. It depends on how you spend the money, whether you itemize, and whether your combined qualifying mortgage debt fits within the $750,000 cap.
That means a kitchen remodel and a credit card payoff can produce very different tax results, even when you borrow the same amount against the same house.
You can often keep your existing first mortgage while borrowing through a HELOC or home equity loan. Our guide to getting equity out of your home without refinancing explains those options. Here's how to think about the interest deduction before counting on it in your budget.
The money has to improve the home securing the loan
The rule is specific. You must use the money to buy, build, or substantially improve the home that secures the loan. Having your house serve as collateral doesn't make every expense qualify.
These projects meet the improvement test when they're for that home, though you still need to clear the itemizing and debt limit hurdles:
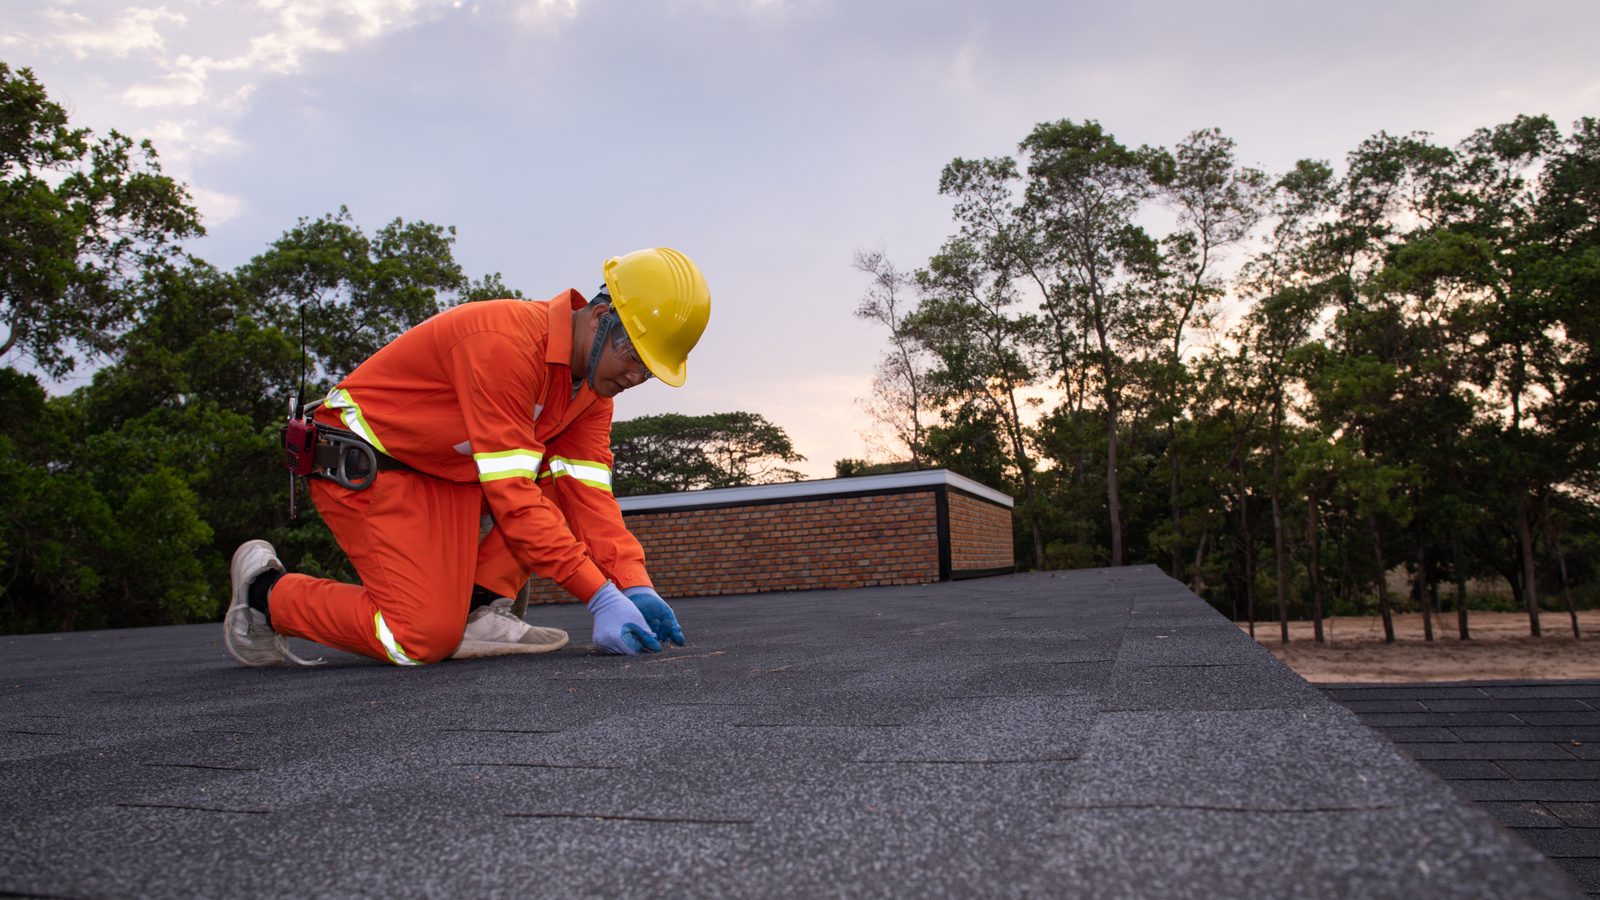
- A new roof replacing the old one.
- A kitchen remodel with new cabinets, counters, and permanent fixtures.
- An addition that gives you another bedroom or more living space.
These uses don't qualify for the home equity loan interest deduction:
- Paying off credit cards, even if the new rate is lower.
- Buying a car.
- Paying tuition.
- Taking a vacation.
Debt consolidation might still help your monthly budget. Just evaluate that decision without a tax deduction built into the savings. And remember that you're putting your home behind the debt.
The spending test applies to both a HELOC and a fixed home equity loan, also called a HELOAN. The product name doesn't decide the tax result. What the borrowed dollars paid for does.
Itemizing is the hurdle people miss
Most filers take the standard deduction. If you do, qualifying home equity interest won't give you a separate deduction on top of it.
The deduction helps only when your total itemized deductions beat your standard deduction. So a qualifying renovation isn't enough by itself. You need to look at your whole return.
There's another wrinkle in the savings estimate. If you already itemize without the new loan interest, the added qualifying interest can have a clearer benefit. If the interest only pushes you slightly above the standard deduction, your added tax benefit can be much smaller than you expected.
Before signing a loan based on expected tax savings, have your tax professional compare those totals. Build your payment budget around what you can afford without the deduction. Treat a confirmed tax benefit as a bonus.
The $750,000 cap is shared
The $750,000 acquisition-debt cap applies to your combined qualifying debt, including your first mortgage and qualifying home equity borrowing. It isn't a fresh $750,000 allowance for each loan, and it isn't a limit on the dollar amount of interest you can deduct. For example, a $400,000 qualifying first mortgage plus a $50,000 loan for a kitchen remodel totals $450,000, below the cap. If your combined qualifying debt exceeds $750,000, don't assume all the interest is deductible; have your tax professional determine the allowed amount.
Mixed-use draws need a paper trail
A HELOC lets you borrow as expenses arrive. That flexibility makes recordkeeping especially valuable if you're using the line for more than one purpose.
Suppose you draw $20,000 for a new roof and another $10,000 to pay off cards. The roof spending may support deductible interest, subject to the other rules. The card payoff doesn't. The deductible share follows the use of the money.
Track what each draw paid for. Keep the draw date and amount alongside the contractor invoice, receipts, and proof of payment. If one draw covers multiple expenses, record how much went to each.
Don't apply a quick percentage to your annual interest and assume you're done. Draw timing and changing balances mean your records need to show how the money moved. Give those records to your tax professional to calculate the qualifying share.
What your Form 1098 tells you
Your lender sends Form 1098 to report mortgage interest paid. Keep it with your loan statements and renovation receipts when you prepare your tax return.
The form reports interest; it doesn't prove that every dollar is deductible. Your lender's interest total can't tell the whole story about contractor payments, card payoffs, or your decision to itemize.
Check the form against your records. If something looks wrong, contact your lender. For mixed-use borrowing, bring both the form and your spending breakdown to your tax professional.

A $50,000 kitchen remodel example
Say you take a $50,000 HELOAN at a fixed 7.4% rate and spend all of it remodeling the kitchen in the home securing the loan. The 7.4% is an illustrative rate, not an Oxford quote.
Assume you pay roughly $3,600 in first-year interest as you make payments and reduce the balance. Your actual interest depends on the loan term, payment schedule, and when the loan starts.
You already itemize, your combined qualifying debt is below $750,000, and the full deduction reduces income taxed at 22%. The estimated federal tax savings are straightforward:
$3,600 × 22% = $792.
That leaves about $2,808 in interest cost after the assumed tax savings. It doesn't include fees or principal payments. You still make the loan payments as scheduled; the deduction doesn't reduce your lender's bill.
A deduction reduces taxable income. It isn't a dollar-for-dollar refund of your interest. If you take the standard deduction instead, this example's $792 benefit doesn't apply.
Choosing the borrowing format is a separate decision. A fixed loan can fit a known contractor price, while a line can fit work billed in stages. Our HELOC versus HELOAN comparison walks through that choice.
When a cash-out refinance still wins
If your first mortgage has a 3% rate, replacing the entire balance to fund a remodel deserves close scrutiny. A second loan can preserve that rate, though it adds another payment. Read how a HELOC works as a second mortgage before comparing offers.
A cash-out refinance can still win if your existing rate is high enough that replacing it improves the overall math. Compare closing costs, repayment terms, and total interest across both options. A potential deduction shouldn't rescue an expensive loan.
Oxford is a lender, not a tax advisor. Confirm your eligibility and expected tax savings with a tax professional.
Frequently asked questions
Can you deduct home equity loan interest?
Yes, if the money buys, builds, or substantially improves the home securing the loan, you itemize, and the interest falls within the combined $750,000 acquisition-debt limit. Using a fixed home equity loan instead of a HELOC doesn't remove those requirements.
Does the HELOC tax deduction 2026 rule cover credit cards?
No. Interest on money used to pay off credit cards doesn't qualify for this deduction. A lower borrowing rate may still save you money, but calculate that savings without a tax benefit and consider the risk of securing the balance with your home.
Is Form 1098 enough to claim the deduction?
No. Form 1098 reports interest paid, but eligibility also depends on your spending, itemizing, and combined qualifying debt. Keep receipts and draw records so your tax professional can connect the interest to qualifying work on the home securing the loan.
Request a free equity review with an Oxford licensed mortgage banker to compare payments and borrowing options for your project before you commit.
Other Articles

Still have a question?
No problem. Let’s just talk.

About Oxford
Refinance Loan
Resources & Calculators
Hire
Advertised offers are not guaranteed if you do not continue to meet Oxford Home Lending's criteria and other factors bearing on your creditworthiness. Rates will vary depending on your loan term, loan type, credit profile & score, down payment, qualifying ratios, and property collateral. Monthly payments do not include property taxes, property insurance, and homeowners' association dues. Since costs can vary based on a loan program, closing costs are not shown in the examples. To qualify for a mortgage, borrowers must be U.S. citizens or permanent residents, and meet Oxford Home Lending's underwriting and Investor requirements. Interest rate examples are as of 03/03/2026 and subject to change without notice. All loans are subject to underwriting or investor approval. Other restrictions may apply. This is not an offer of credit or a commitment to lend. Rate subject to change depending on time of lock.
Lower, LLC DBA Oxford Home Lending | NMLS #1124061 | www.nmlsconsumeraccess.com.
Lower, LLC | NMLS ID# 1124061 | 5950 Symphony Woods Road Suite 312 Columbia, MD 21044 | Equal Housing Opportunity | https://nmlsconsumeraccess.org/ | Not an offer of credit or commitment to make a loan; all approvals are subject to underwriting guidelines including but not limited to acceptable current credit worthiness, income history, debt ratio, etc. Loan programs & options are subject to change at any time. Rates will vary depending on your loan term, loan type, credit profile, down payment, and qualifying ratios. Rates can change daily. Some restrictions may apply. No statement herein should be construed as being made on behalf of any state or federal agency.
© 2026 Lower, LLC | Conducts business in 47 States to include the District of Columbia. Alabama, Alaska, Arizona - License #1000936, Arkansas, California, Colorado, Connecticut, Delaware, District of Columbia, Florida, Georgia, Idaho, Illinois, Indiana, Iowa, Kansas, Kentucky (Lower.com, LLC), Louisiana, Maine, Maryland, Massachusetts Mortgage Broker License -- MC1124061 | Massachusetts Mortgage Lender License -- MC1124061, Michigan, Minnesota, Mississippi, Missouri, Montana (Lower.com, LLC), Nebraska, New Hampshire, New Jersey, New Mexico, Nevada, North Carolina, North Dakota, Ohio, Oklahoma (Lower Mortgage, LLC), Oregon, Pennsylvania, Rhode Island, South Carolina, South Dakota, Tennessee, Texas, Utah, Virginia, Washington (Lower.com, LLC), West Virginia, Wisconsin, and Wyoming.
Refinance: By refinancing your existing loan, your total finance charge may be higher over the life of the loan.
Reviews: Zillow® is a trademark of Zillow, Inc. Bankrate® is a trademark of Bankrate, LLC. Lending Tree® is a trademark of Lending Tree, LLC. Google® is a trademark of Google LLC. Facebook® is a trademark of Facebook, Inc.